Wrong VWAP Indicator
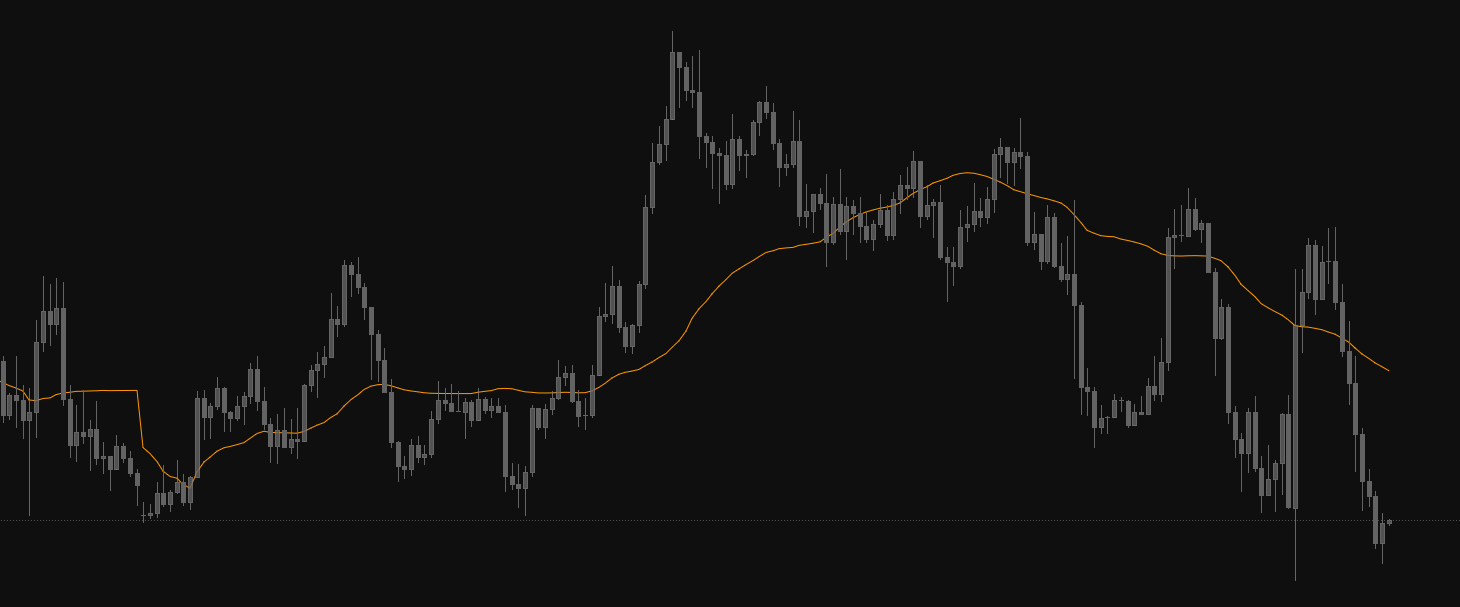
I want to thank you guys for your work and i don`t want to sound ungrateful but you guys made the wrong VWAP indicator, you guys made a Rolling VWAP NOT the Actual VWAP.
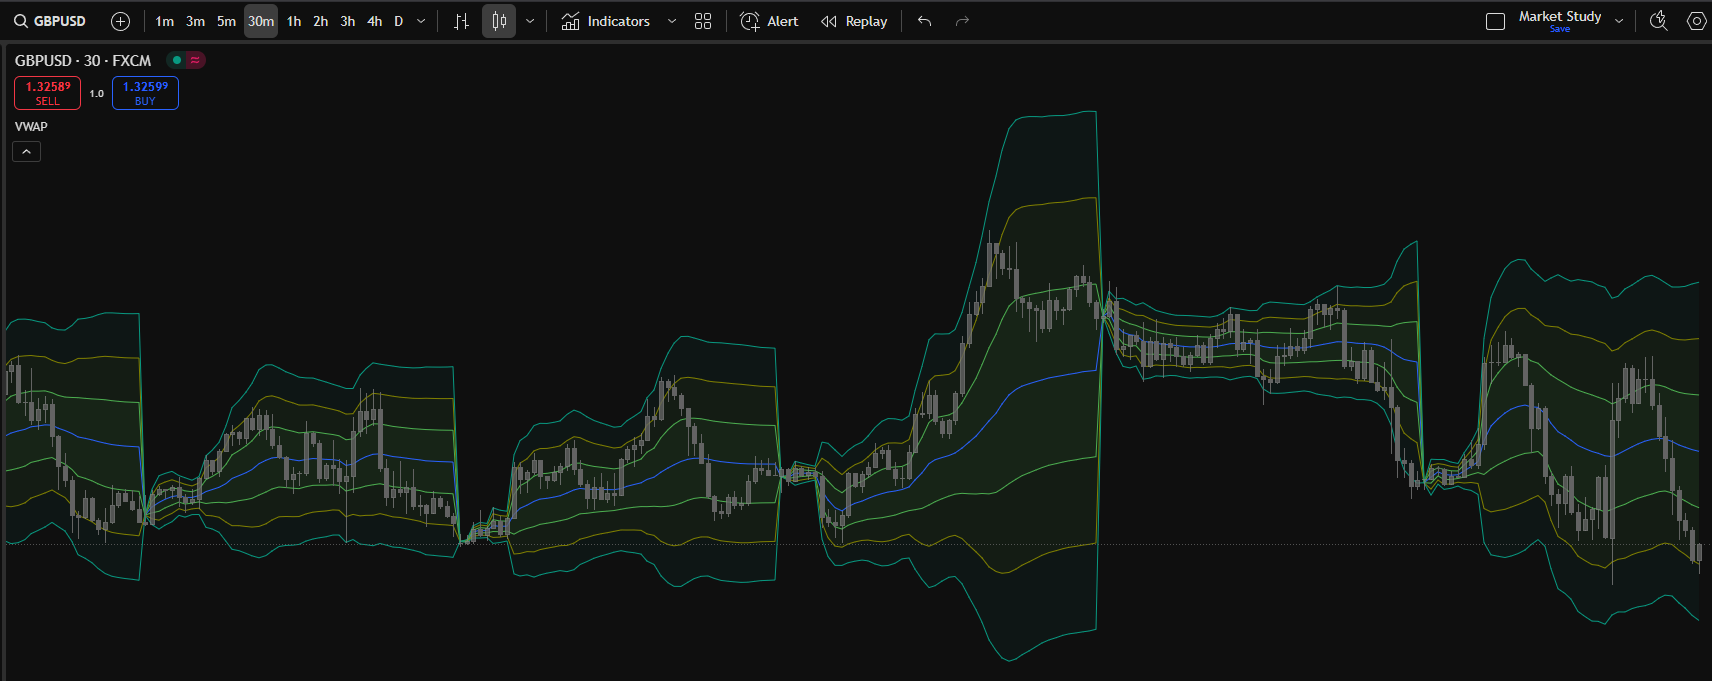
I`m deeply thankful for your work and i don`t want to clog up your task log with more requests but please add the real VWAP like the the bottom pictures.
The Rolling VWAP takes an input period 14 period default in FTO.
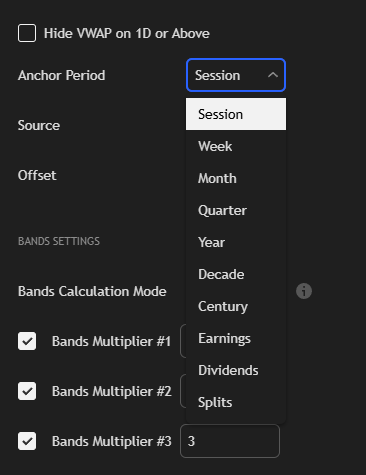
The VWAP (Actual) is calculated based on trading session, Day, Week, Month etc… and a new VWAP will form at the start of the new period, an each VWAP Has its own +2 and +3 standard deviations,
- How does this impact your experience?
This request was merged into another request
Comments1
Roman F
May 9, 2025
Dear @AxeP . Thanks for the information, I’ve sent this request to developers and we’ll contact you, when it’s implemented. Please, stay tuned.